Buying a home is an investment because it builds equity through monthly mortgage payments while allowing owners to profit from long-term property appreciation. This process transforms a standard living expense into a wealth-building asset; additionally, it provides tax deductions and recoverable costs that typically outperform renting. Understanding how is buying a home an investment is essential for building generational wealth and securing long-term financial stability.
Many international investors view residential property as a simple asset; yet they often struggle to turn that initial purchase into a consistent, wealth-generating engine. Without a firm grasp of cash flow mechanics, a home remains a liability rather than a true investment. At KLR Real Estate Consulting Services, we recognize that sophisticated wealth management requires more than just holding title. It demands a precise understanding of how equity and income work in tandem. This guide provides an expert analysis of the mechanics behind real estate wealth, from evaluating specific profitability benchmarks like the 2 percent rule to optimizing your tax position through LLC structures. You will learn why the Midwest market offers unparalleled stability for remote owners and how to transform a physical property into a streamlined, passive asset that serves your long-term financial objectives.
Understanding Why Buying a Home Is Considered a Strategic Investment
To the casual observer, a house is a place of residence, yet for the sophisticated investor, a residential property functions as a productive capital asset. When asking how is buying a home an investment, it is essential to distinguish between the utility of a primary residence and the mechanics of a rental acquisition. For domestic owners, a home acts as a mechanism for forced savings, where monthly mortgage payments slowly convert debt into equity. However, for the international clients we serve through our data-driven investment consulting, the primary objective shifts from simple equity accumulation to consistent income generation.
Industry research highlights a stark wealth creation gap, revealing that the median net worth of a U.S. homeowner is roughly 40 times that of a renter. This disparity stems from the compounding nature of real estate assets over time. For international investors, this wealth building is further enhanced by holding USD-denominated equity, providing a robust hedge against currency volatility in their home markets. By utilizing tax-focused financial coordination, these investors transform a physical structure into a yield-bearing instrument that produces monthly cash flow while simultaneously capturing long term value growth. This transition from home as shelter to home as strategic asset is the foundation of a successful Midwest portfolio.
The Mechanics of Real Estate Wealth: How Homeownership Builds Value Over Time
Building on the significant wealth gap between homeowners and renters, it is necessary to examine why real estate creates more sustainable value than traditional liquid savings. While a high yield savings account offers a predictable but modest return, it lacks the multi dimensional growth found in a residential asset. The primary advantage of Milwaukee real estate investment lies in the synergy of four distinct wealth pillars that work simultaneously to compound capital.
The first pillar is appreciation, which is the historical increase in property value over time. Second is principal paydown, often described as an externalized savings plan. In this model, the tenant's monthly rent payments service the mortgage debt, effectively transferring the bank's capital into the investor's equity. Third, tax-focused financial coordination allows investors to leverage depreciation, a non cash expense that can offset taxable income. Finally, monthly cash flow provides the immediate liquid return that validates the acquisition. These pillars demonstrate why, when looking at the core metrics, the answer to how is buying a home an investment is found in the total return rather than just one single factor.
When analyzing how buying a home builds wealth vs renting, the distinction becomes most apparent over a seven year horizon. Short term holding periods are frequently impacted by acquisition costs and market fluctuations; however, the seven plus year mark is the recognized sweet spot for compounding returns. During this period, the combination of rising rents and a decreasing mortgage balance accelerates equity growth far beyond what is possible in a standard savings account. For the international investor using data-driven investment consulting, this means that while the property remains a physical asset in the U.S., the financial mechanics are working to build a diversified, USD denominated legacy that hedges against global economic volatility.
Evaluating Rental Profitability: The 2 Percent Rule and The 7 Percent Rule
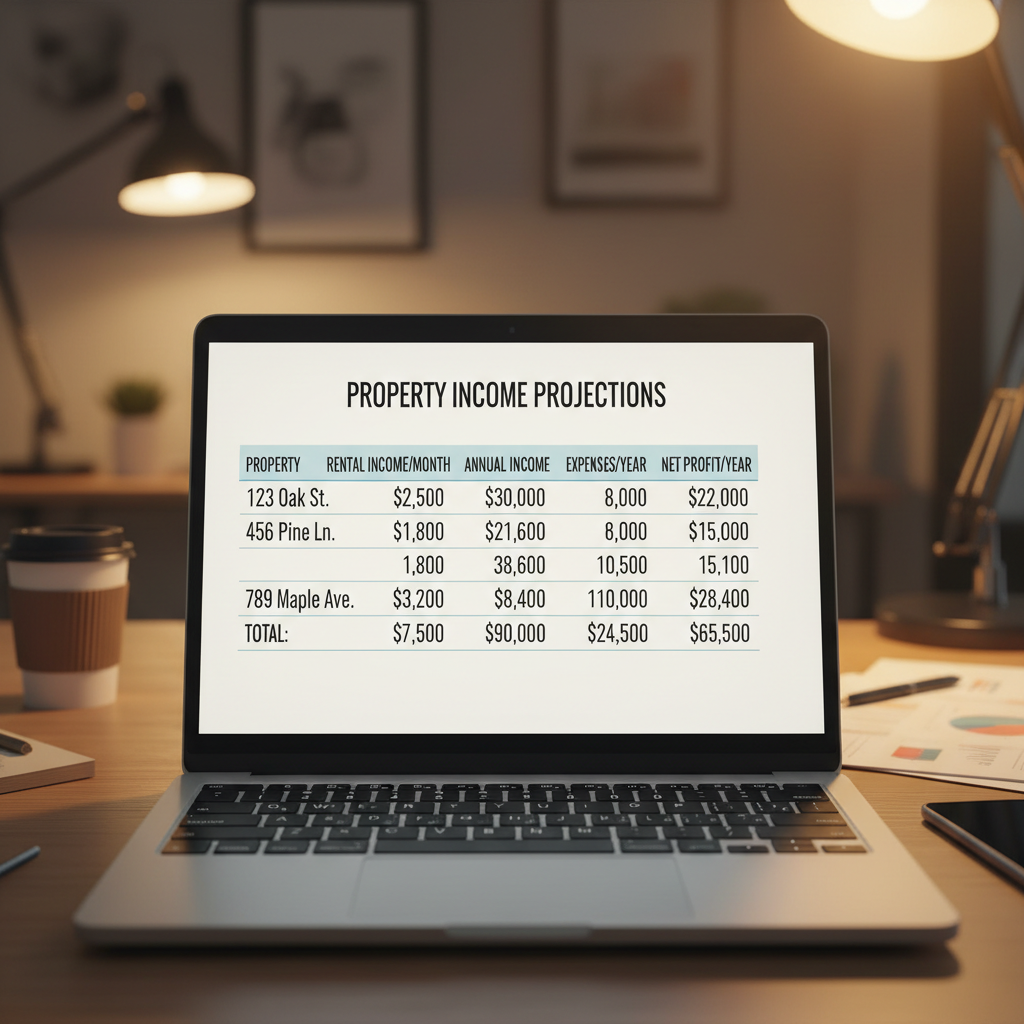
To quantify how is buying a home an investment in a practical sense, investors often look to two primary heuristic filters: the 2% Rule and the 7% Rule. These metrics provide a quick assessment of a property’s potential to generate immediate cash flow before moving into a more rigorous data-driven investment consulting process.
The 2% Rule suggests that a rental property is a strong candidate if the monthly rent equals at least 2% of the total purchase price. For example, a property purchased for $150,000 would ideally command $3,000 in monthly rent. However, in modern, stable environments like the Milwaukee real estate investment market, achieving a full 2% often requires entering higher-risk areas with significant maintenance overhead. For most international clients, a 1% ratio is a more realistic and sustainable benchmark for high-quality, residential assets in stable neighborhoods. This 1% threshold still provides a healthy margin for operating expenses while ensuring the property remains competitive.
The 7% Rule serves as a secondary filter, focusing on the cost of capital. Historically, this rule suggests that if mortgage rates exceed 7%, the property’s capitalization rate must be significantly higher to maintain positive leverage. Alternatively, it serves as a benchmark against the historical average return of the stock market; if an investment is not projected to yield at least 7% annually through combined cash flow and appreciation, the risk may not be justified. For our clients, these rules are merely the starting point. Before acquisition, we utilize tax-focused financial coordination to refine these numbers, accounting for international tax treaties and specific local property taxes to ensure the projected yields translate into actualized wealth.
Cash Flow vs Appreciation: Why the Midwest Market Offers Unique Stability
Moving beyond general heuristics requires an understanding of regional market dynamics. When considering how is buying a home an investment, geography dictates the primary driver of your return. In coastal markets like California or New York, investors often rely on speculative appreciation, betting that property values will climb faster than inflation despite negative or neutral monthly cash flow. In contrast, Milwaukee real estate investment and the broader Appleton market prioritize immediate, reliable yield. These Midwest corridors offer a lower cost of entry combined with a higher rent to value ratio, ensuring that the property pays for itself from day one while providing a surplus for the owner.
The Midwest serves as a stabilizer for international capital because it is historically insulated from the extreme volatility seen in speculative bubbles. While coastal prices may skyrocket and then retract sharply, residential properties in Wisconsin tend to maintain steady, incremental growth. This stability is rooted in local economic fundamentals; a diversified job market and a reasonable cost of living sustain consistent tenant demand. Through data-driven investment consulting, we identify assets that act as a direct hedge against inflation. As the cost of goods rises, residential rents in these stable markets typically follow suit, preserving the real value of the investor’s monthly income. This predictable performance is why sophisticated portfolios often lead with Midwest residential assets to balance out more aggressive, higher risk holdings. Our approach to tax-focused financial coordination further ensures that these stable returns are optimized for the specific residency and tax status of our international clients.
How to Buy a Rental Property With an LLC for Tax Optimization
Establishing a secure legal framework is a critical step in actualizing the returns discussed in previous sections. For international investors, the structural vehicle used to hold an asset is just as vital as the asset itself. Using a Limited Liability Company (LLC) transforms the acquisition from a personal purchase into a professional business operation. This distinction is fundamental when evaluating how is buying a home an investment, as the LLC provides a clear boundary between personal global assets and U.S. based real estate liabilities.
Asset protection remains a primary driver for this structure. By holding Milwaukee real estate investment properties within an LLC, an investor limits their exposure to the value of the property and its insurance coverage, shielding personal wealth from potential litigation or external claims. Furthermore, through tax-focused financial coordination, an LLC can be structured as a pass through entity. This simplifies the tax filing process for non U.S. residents by allowing income and expenses to flow directly to the owners; it often provides a more streamlined path for claiming depreciation and interest deductions without the complexity of personal U.S. tax filings for every individual involved.
The administrative efficiency of an LLC also facilitates cleaner accounting. Professional separation of business finances ensures that property related expenses, from maintenance to mortgage interest, are easily tracked for annual reporting and compliance. KLR Real Estate Consulting Services assists international clients with this coordination, ensuring that the legal and financial setup aligns with the long term goals identified during data-driven investment consulting. This structural preparation ensures that the property functions as a legitimate business entity, ready for the remote management protocols necessary for scalable passive income.
The Realities of Remote Management: Turning a House into a Passive Asset
Transitioning from legal structure to operational reality is where many international portfolios either thrive or falter. While the initial acquisition data demonstrates how is buying a home an investment, the actualization of that yield depends entirely on turning a physical structure into a professionally managed asset. For an owner located thousands of miles away, the passive nature of the income is not inherent; it is manufactured through rigorous ongoing portfolio oversight and local expertise.
Successful Milwaukee real estate investment requires more than just securing a deed. It involves full acquisition management, which encompasses everything from the initial inspections and rehabilitation to the final tenant placement. Once the property is occupied, the mechanics of cash flow are protected by active management that mitigates risks such as high vacancy rates or poorly vetted tenants. Without this layer of professional intervention, the four pillars of wealth, particularly cash flow and principal paydown, can be quickly eroded by operational inefficiencies or deferred maintenance.
In the Milwaukee and Appleton markets, local knowledge is a non negotiable requirement for remote owners. Navigating Wisconsin's specific municipal codes and seasonal maintenance demands requires a boots on the ground approach that a remote investor cannot provide independently. By integrating data-driven investment consulting with tax-focused financial coordination, investors ensure that their U.S. assets are not just purchased, but optimized. This professional oversight allows the investor to focus on high level portfolio strategy while the day to day complexities are handled by experts dedicated to preserving the property's value and maximizing its long term performance.